All Categories
Featured

How Whole Life Insurance Works
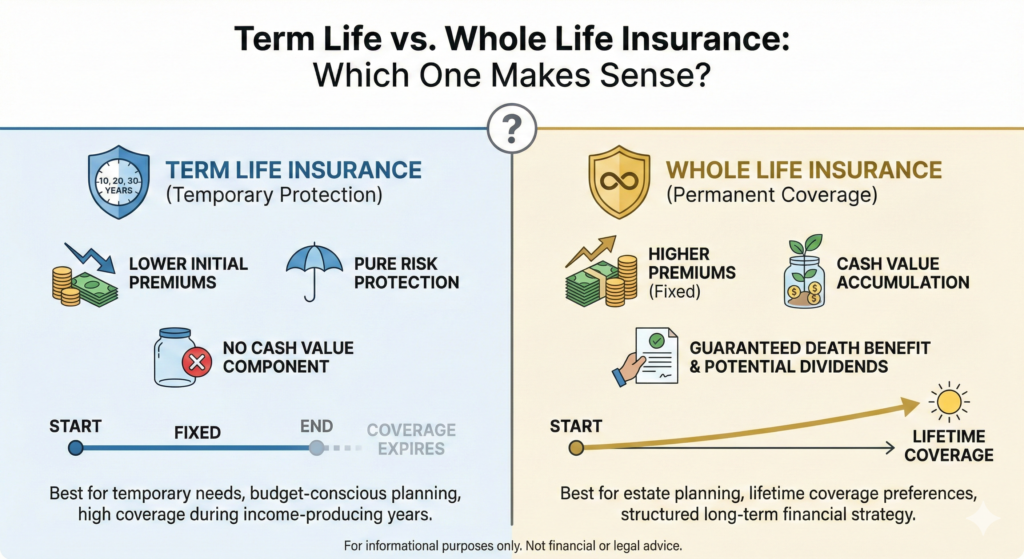
An entire life insurance coverage policy in a very actual sense is more than simply life insurance. It's a flexible financial instrument that helps secure families and companies from uncertainty while helping them build and improve wealth. If that is necessary to you, this short article can help respond to crucial questions, including: Entire life insurance coverage is, primarily, long-term life insurance coverage protection that lasts your whole life; by contrast, term life insurance only covers you for a specific variety of years.
Entire life insurance coverage policies also have a "cash value" element a life-long financial property. 1 Since life insurance protection is thought about useful to society, it has been provided tax benefits you may not discover with numerous other financial instruments. 2Every entire life contract is unique to the guaranteed person, taking into account their mortality risk, wanted protection level, and optional functions (for instance, a cost-of-living change rider).3 When you look for a whole life policy, there's an underwriting process in which you might go through a medical examination.
Then, based on your life span, the insurance provider's actuaries set four guaranteed values4: A guaranteed level premium: Whole life insurance coverage policies have repaired premiums that are guaranteed never ever to change. As long as you keep making premium payments, the policy will remain in result, and each premium payment contributes to the policy's money worth.
A surefire cash worth: A cash worth that is guaranteed to grow at a set rate each year until it amounts to the face quantity of the policy at a specified age, typically age 100 or 121. A guaranteed endowment: The survivor benefit is ensured to be paid if the insured is still living at the age defined in the agreement, usually age 100 or 121. A part of each premium payment is allocated to a cash worth account, which grows in time.
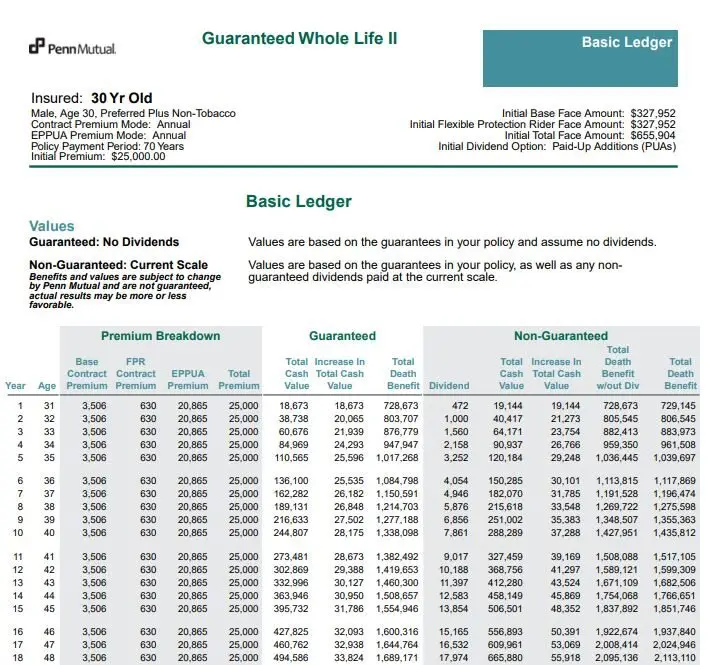
It can take time for it to grow into a helpful quantity, but as soon as that occurs, you can borrow cash against your policy's money value, utilize it to pay premiums, and even surrender it for cash in retirement. 5If you acquire whole life from a mutual insurance provider, such as Guardian, the cash value part can likewise earn yearly dividends, which can increase your money value beyond the ensured rate. While there's no assurance that dividends will be stated each year, Guardian has paid them every year since 1868, even during wars, pandemics, or stock market turbulence. Depending upon your requirements, you can choose to utilize your dividends in different ways. One choice is to acquire paid-up additions (PUAs).7 A PUA is ensured permanent, paid-up life insurance.
Final Expense and Burial Expense Planning
Over time, the intensifying accumulation of PUAs can help to offset the impacts of inflation by offering a greater death advantage and cash worth. Dividend accumulations can also be withdrawn income tax-free, up to the policy basis (i.e., the amount of premiums paid to date).
It can also provide numerous other monetary advantages. The majority of people see the significance of insuring the value of residential or commercial property, such as their home or car, so they acquire casualty insurance. The human life value8 of a specific one of the most important possessions of a household or service is also insurable.
The survivor benefit of life insurance can assist guarantee the economic connection of a family when it is confronted with the death of an enjoyed one, by assisting offer funds that can be used for: Payment of a mortgageEducation fundingIncome needsTime far from work to look after household needsFuneral expenses Arrearages Organizations wanting to develop an organization connection method in case of the death of a partner or key worker have special insurance coverage needs.
Life insurance coverage can help address four major areas of company strategies: The funding of buy-sell agreements and stock redemption plansThe financing of additional retirement programsKey person indemnificationPayment of loans and home loans Preparation for the orderly transfer of residential or commercial property at death can assist to lessen taxes and offer heirs in such a way that reflects your desires.
It can make it possible for the policy owner to utilize estate possessions in manner ins which may not be possible otherwise. It can be the "permission slip" that lets you make use of other aspects of your retirement earnings and personal net worth. It can give you the power to invest properties that might not otherwise be used.

Latest Posts
Why IUL Insurance Works
Final Expense and Burial Insurance for Families
Reviewing PPO Vs HMO Health Insurance for 2026