All Categories
Featured

How Term Life Builds Future Wealth
Table of Contents
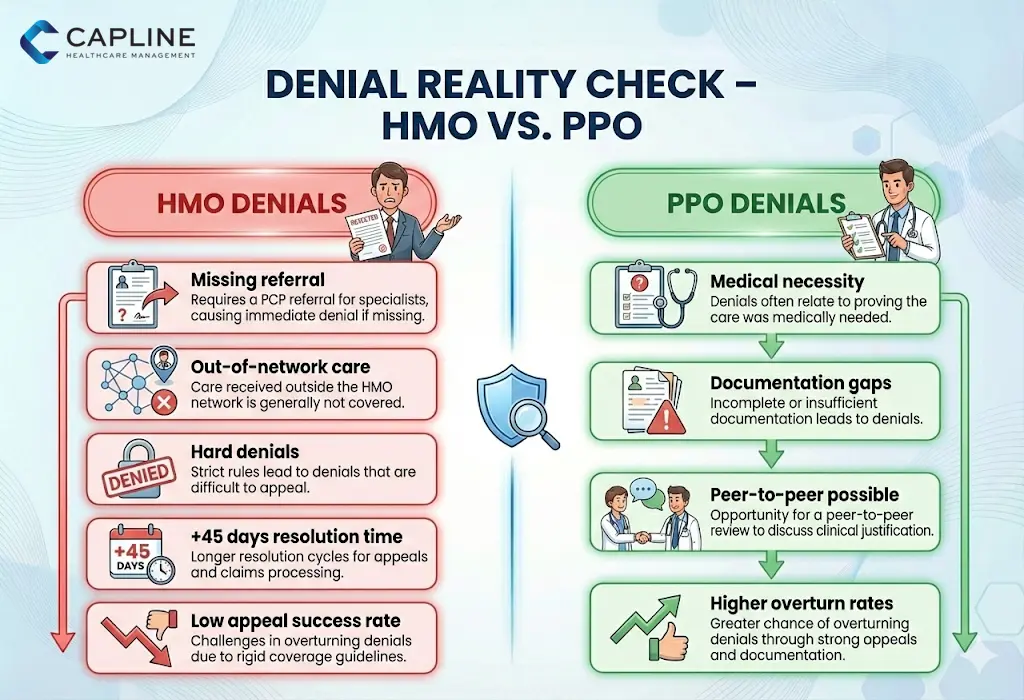
Like all health insurance, getting in-network care is best to keep your out-of-pocket costs low. Nevertheless, unlike HMO strategies that won't cover any portion of your bill if you seek out-of-network care (other than in a covered emergency situation), you can get out-of-network care when taking a trip out of your routine plan network area with a PPO policy.
Insurance in Jurupa Valley CACost-conscious people should think about a couple of disadvantages to PPO plans that might make getting care more pricey. While they're versatile and practical, PPO strategies have higher premiums. According to KFF, PPO strategies had the greatest annual premiums compared to HMOs and point-of-service strategies (POS) in 2023. You'll also have to pay more expensive medical bills if you get care from an out-of-network supplier.

If you do have a deductible, it's likely to be more pricey than other plan types. While your insurance provider will share the expense with you, you'll likely pay a higher coinsurance percentage for out-of-network providers. When you go to an in-network service provider, they'll file your claim to your health insurance business on your behalf.
PPO policyholders might find the claim filing procedure made complex if they're not utilized to it or time-consuming if they frequently need out-of-network care from a specialist. In 2023, the typical yearly premium for a group PPO plan was $8,906 for self-only protection and $25,228 for household coverage2. Companies contributed $7,399 towards a self-only strategy, and workers contributed $1,507.
Finding Affordable Individual Health Coverage
The average deductible for PPO plans was $1,281. As discussed above, PPO plans acquired on the ACA marketplaces also have an optimum out-of-pocket limit of $9,450 for self-only coverage and $18,900 for family strategies.

Yes No Yes No Some plans do. A lot of plans do. Whether you have an HMO or PPO plan, you can leverage a health compensation arrangement (HRA) to lower out-of-pocket medical costs.
Insurance in Jurupa Valley CAJust companies can introduce and contribute toward an HRA. Companies use an HRA to give their employees a regular monthly allowance to spend for medical expenses. When a staff member buys a qualified item or service, they submit documentation revealing proof of purchase, and their employer compensates them up to their allowance amount.
Essential Part D Enrollment Tips in 2026
(MEC). (ICHRA): An ICHRA is also a stand-alone HRA, however it's readily available to companies of all sizes and has no contribution limitations.
They should have a certifying form of specific health protection to take part. Companies can set different allowances based on staff member classes for added customization. Group protection HRA (GCHRA): Likewise referred to as an integrated HRA, a GCHRA is for companies of any size who use a group health plan. Just employees registered in their company's group strategy can take part.
While they have no maximum contribution limits, the IRS does not allow repayments for monthly premiums. No matter whether it's used in coordination with an HMO or PPO strategy, there's an HRA that can help employees spend for their out-of-pocket medical expenses and, in some cases, their health insurance coverage premiums. An HRA is a popular alternative choice over standard health advantages due to the fact that they're economical for companies and flexible enough for each staff member.
Why Whole Life Protects Family Wealth
An HMO may be your best option if you're trying to find a plan with a low premium. A PPO plan supplies additional flexibility if you require more control over your health care. That's why investigating these plans carefully, including their pros, cons, and average costs, is the finest primary step you can take before making a decision.
(MEC). (ICHRA): An ICHRA is likewise a stand-alone HRA, but it's readily available to companies of all sizes and has no contribution limitations.
But, they need to have a certifying type of private health coverage to get involved. Employers can set different allowances based upon worker classes for included modification. Group coverage HRA (GCHRA): Also referred to as an incorporated HRA, a GCHRA is for companies of any size who offer a group health insurance. Only staff members registered in their company's group plan can participate.
2026 Term Life Insurance Rates for Families
While they have no optimum contribution limits, the IRS doesn't allow compensations for month-to-month premiums. No matter whether it's utilized in coordination with an HMO or PPO plan, there's an HRA that can assist workers pay for their out-of-pocket medical expenses and, in some cases, their medical insurance premiums. An HRA is a popular alternative option over standard health benefits because they're economical for employers and flexible enough for every single employee.
An HMO may be your best bet if you're trying to find a plan with a low premium. However, a PPO strategy supplies extra flexibility if you require more control over your health care. That's why looking into these plans carefully, including their pros, cons, and average costs, is the best initial step you can take in the past making a choice.

Latest Posts
Getting Affordable 2026 Family Health Insurance

Choosing Whole Life versus Term Plans
How Term Life Builds Future Wealth